When people think about investing, one of the first questions they’re often asked is, “How much risk are you comfortable taking?”
It sounds like a simple enough question, but the answer is only one piece of a much bigger picture.
At Lazenby’s, we don’t believe investment decisions should be based solely on how adventurous or cautious someone feels. Just because you’re comfortable with taking risk doesn’t necessarily mean it’s the right level of risk for your circumstances.
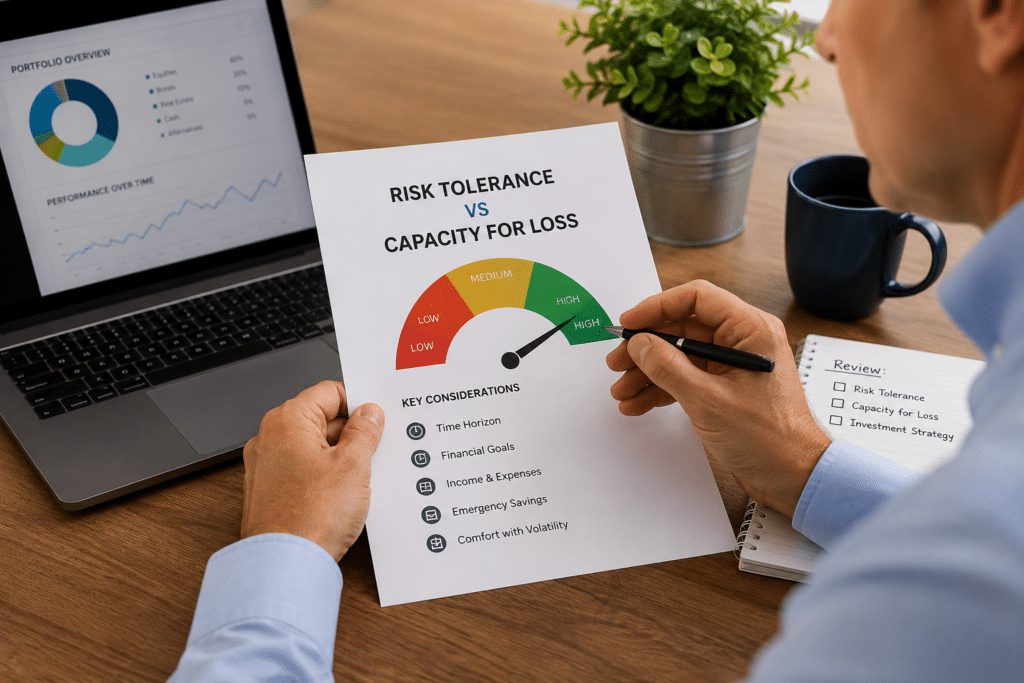
Two important concepts help shape investment decisions: attitude to risk and capacity for loss. They sound similar, but they mean very different things.
What is attitude to risk?
Your attitude to risk is exactly what it sounds like – it’s your personal comfort level when it comes to investing.
Some people are happy to accept ups and downs if it means they have the potential for higher long-term returns. Others prefer a smoother journey, even if that means accepting lower growth.
There isn’t a right or wrong answer. It’s about understanding how you feel when markets inevitably fluctuate.
A person with a higher attitude to risk might not lose sleep if their portfolio falls by 15% during a difficult year, whereas someone else may find even a small drop extremely worrying.
Understanding this emotional response is important because investing should never leave you feeling constantly anxious or tempted to make rushed decisions.
What is capacity for loss?
Capacity for loss is something completely different.
Rather than asking “How would you feel if your investments fell?”, it asks:
“If your investments did fall, what would the impact actually be on your life?”
It’s a financial question rather than an emotional one.
For example, imagine two people both have £300,000 invested.
One plans to retire in six months and will rely heavily on that money to generate an income.
The other is 25 years away from retirement, has a secure income and doesn’t expect to touch their investments for decades.
Although they have the same amount invested, their capacity for loss is very different.
The person approaching retirement may struggle to recover from a significant market fall. The younger investor has much more time for markets to recover and continue growing over the long term.
Why they’re not the same
This is where people often get caught out.
You may feel perfectly comfortable taking high levels of investment risk, but financially you may not be able to afford significant losses.
Equally, someone might be naturally cautious yet have a strong financial position and a long investment horizon, meaning they could afford to take more investment risk than they realise.
That’s why attitude to risk and capacity for loss should always be considered together.
One reflects your personality.
The other reflects your financial reality.
Time really does matter
One of the biggest factors affecting investment risk is how long your money will remain invested.
Markets rise and fall. That’s entirely normal.
History has shown that while markets experience short-term volatility, they’ve generally rewarded patient investors over longer periods.
If you’re investing for a goal that’s 15 or 20 years away, temporary market downturns are often less concerning than if you need the money next year.
On the other hand, if you’re planning to buy a property, fund university fees or retire in the near future, taking excessive investment risk could leave you needing to withdraw money at exactly the wrong time.
Your investment timescale plays a huge role in determining what’s appropriate.
Don’t overlook your emergency savings
Another factor that’s often forgotten is having enough accessible cash.
If every pound you own is invested, you may be forced to sell investments during a market downturn simply because an unexpected expense crops up.
Having an emergency fund for life’s surprises can help protect your long-term investments from being disturbed at the wrong time.
It’s also worth thinking about any major spending plans over the next few years.
Perhaps you’re planning home improvements, helping children onto the property ladder or buying a new car.
Money you’ll need in the near future may be better kept somewhere less exposed to market volatility.
Income matters too
The way you rely on your investments also influences how much risk may be appropriate.
If you’re still working and your investments are simply growing for the future, you may be able to ride out periods of market volatility more comfortably.
However, once you’re drawing an income from your investments, things become more delicate.
Taking withdrawals while markets are falling can have a greater impact on how long your money lasts, making the level of investment risk even more important.
That’s why retirement planning isn’t simply about choosing investments – it’s about understanding how they’ll support your lifestyle for years to come.
A questionnaire is only the starting point
Many investment firms ask clients to complete a risk questionnaire.
These can be useful, but they’re only one part of the conversation.
A few multiple-choice questions can’t fully understand your family circumstances, future plans, income requirements or financial commitments.
At Lazenby’s, we use risk profiling as a starting point rather than the final answer.
We take the time to understand your wider financial picture, helping ensure your investment strategy reflects not only your attitude to risk, but also your capacity for loss and your long-term objectives.
Life changes – and so should your investment strategy
The right level of investment risk isn’t something you choose once and forget about.
Life moves on.
You might change jobs, receive an inheritance, start a family, retire, pay off your mortgage or experience changes to your health or income.
Each of these events could alter both your attitude to risk and your capacity for loss.
That’s why regular reviews are so valuable. They help ensure your investments continue to reflect your circumstances rather than the ones you had five or ten years ago.
The bigger picture
Successful investing isn’t about taking the highest possible risk in pursuit of the biggest returns.
It’s about taking the right level of risk for you.
That means understanding not only how comfortable you are with market ups and downs, but also how much financial risk you can realistically afford to take.
At Lazenby’s, we believe every investment decision should be built around your personal circumstances, your future plans and your financial goals—not just the answers on a questionnaire.
If you’re unsure whether your current investments still reflect your situation, reviewing your approach could give you greater confidence that your money is working as hard as it should, while taking a level of risk that’s right for you.